Neobank vs Traditional Bank for Expats: Pros and Cons
General information, not advice. This guide explains how things usually work. Fees, rules and products change and depend on your country and situation, so check the provider's or authority's own page before you act. See our disclaimer.
Some links may be affiliate links. They never change what we recommend. How we make money.
When you move abroad, one of the first practical questions is: where do I put my money? A traditional bank in the country where you live feels like the “proper” choice, but it can be slow to open and demanding about paperwork. A neobank opens in minutes on your phone, but you may wonder whether it is a real bank at all.
The truth is that both have strengths and weaknesses for people who live, work or travel across borders, and many expats end up using both. This guide compares neobanks and traditional banks on the points that matter most to expats: opening an account, fees, protection, services, daily use and risks. If you are new to the products that neobanks often offer, start with what a multi-currency account is.
The short answer
- Traditional banks offer the full range of services (loans, mortgages, savings products, in-person support) and are often needed for long-term life in a country, but opening an account usually requires local documents and takes longer.
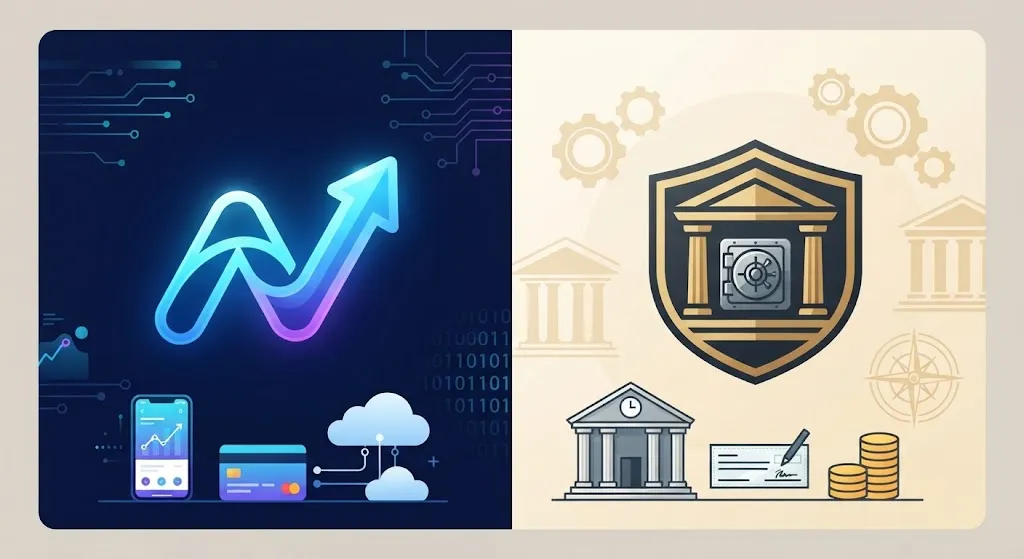
- Neobanks open fast, are often cheaper for international payments and work well for people who move around, but they may lack some services, and the protection of your money depends on whether they hold a banking licence.
- For most expats, the best setup is a combination: a local traditional bank for essentials and savings, and a neobank or multi-currency account for international payments and travel.
What is a neobank?
A neobank is a digital-only financial provider that you use through an app, with no branches. The word covers very different companies:
- Licensed banks that operate only online.
- Electronic money or payment institutions that are not banks, but offer account-like services.
- Apps that partner with a bank and hold your money there.
This difference matters because it decides how your money is protected. A neobank with a full banking licence in your country may offer deposit insurance, while one that is an e-money institution usually safeguards your money instead, which is a different kind of protection. Some neobanks are moving from one model to the other. For example, Revolut announced in March 2026 that it had exited the UK “mobilisation” phase and launched as a fully licensed UK bank, with eligible deposit accounts protected by the Financial Services Compensation Scheme, up to £120,000 per person per authorised firm. At the same time, it said new customers might still be onboarded to an electronic money account while customers are gradually transferred to the bank, so the entity that holds your money can differ depending on when and where you signed up. To understand the types of protection in detail, see how your money is protected.
What is a traditional bank?
A traditional bank is a licensed bank with a long track record, usually with branches and a full set of services: current and savings accounts, loans, mortgages, overdrafts, cards, investments and in-person advisers. It may also have an online banking app, but it is built around a local customer base.
Side-by-side comparison
| Neobank | Traditional bank | |
|---|---|---|
| Opening an account | Usually fast and fully online, often in minutes | Slower; may need an appointment and local documents |
| Proof of address | Often more flexible, though still required in many cases | Usually required, with strict checks |
| Fees for international payments | Often low and transparent | Often higher, with margins on exchange rates |
| Multi-currency features | Common | Limited or expensive |
| Local services (mortgage, loans, overdraft) | Often limited or missing | Full range |
| In-person support | None or limited | Branches and advisers |
| Language support | Usually English-friendly | Varies; some have English services |
| Protection of your money | Depends on whether it holds a banking licence | Usually deposit insurance on eligible deposits |
| Salary and local payments | Sometimes problematic | Normally accepted everywhere |
| Risk of closure or review | Real; automated checks | Real, but often with more human contact |
| Best for | Frequent movers, international payments, new arrivals | Long-term residents, savings, borrowing |
Opening an account
This is where expats feel the biggest difference.
Traditional banks typically ask for ID, proof of address in the country, and often proof of income or a work contract. In practice that creates a loop: you need an address to open an account, and you may need an account to rent a home. Guides for expats note that traditional banks in several countries still demand robust proof of a local residential address for standard current accounts, and that opening can take one to two weeks and involve an in-person appointment.
Neobanks are usually quicker, often needing little more than a passport scan and a selfie, and some do not demand proof of a local address from the start. Be aware that they are still required to verify you and may restrict features if they cannot. Rules vary a lot by country, and a neobank that serves your home country may not serve the country where you now live. If you are struggling with documents, see how to open a bank account as a non-resident.
A common route is to open a neobank account first, use it while you settle in, and then open a local traditional account once you have an address and documents.
Fees
Fees are often a main reason expats choose neobanks. Traditional banks commonly charge account management fees, card fees and higher costs on international transactions, often through a margin on the exchange rate. Neobanks usually have lower fees and more transparent pricing, but there are catches: free plans may limit currency exchange allowances, charge extra at weekends or on large amounts, or cap free ATM withdrawals.
Rather than comparing the headline fees, calculate the total cost on the payments you actually make. Our transfer fee calculator helps you do that.
Cards and daily use
For travel and daily spending, the useful details are the fee for spending in other currencies, ATM limits, whether the card works with your local payment systems and how easy it is to freeze or replace. Neobank apps are generally strong on instant notifications and card controls, while traditional banks may be stronger on local acceptance and in-branch help. If cards matter to you, see our guide to debit cards for international travel.
Savings, loans and mortgages
This is where traditional banks usually win. Neobanks often lack mortgage products, local savings accounts or full pension advice, and the loans or credit they offer can be limited in size or provided through a partner. If you plan to buy a home, need a local credit history or want standard local savings products, a traditional bank is often required.
For long-term goals, build a plan before you choose where to keep what. Our guide on how to save and invest as an expat explains how to split your money between cash, protection and investments.
Protection of your money
As explained above, protection depends on the type of provider. Banks usually have deposit insurance on eligible deposits up to a limit, while non-bank providers usually rely on safeguarding rules. Before you put significant savings into any neobank, check whether it holds a full banking licence in your country, not only a payment institution licence, and which entity actually holds your money. A fully licensed bank can offer the complete range of services you would find at a traditional bank.
Everyday problems expats report
Neobanks are not perfect for expats, and these are the most common issues:
- Salary payments. Some foreign employers or payroll systems do not recognise a neobank account, or the transfer process is more complicated.
- Local payments. Some local services only accept domestic bank details or specific card networks.
- Limited human support. When something goes wrong, you may be dealing with a chatbot and a slow ticket system.
- Limits and reviews. Automated checks can restrict features until you provide documents.
- Access problems. Being abroad and suddenly unable to reach your online account is a common complaint.
- Fewer financial products. Overdrafts, loans, savings accounts and cheque books may be missing.
Risks of neobanks
The risk that matters most in practice is not that the company fails, but that your account is limited, frozen or closed while you are abroad and need the money. Read about this in our guide on why online accounts get closed, and keep a backup so that a review at one provider does not stop your income.
Risks of traditional banks
Traditional banks have their own drawbacks for expats:
- Slow onboarding and demanding paperwork.
- Higher fees for international payments and foreign currency.
- Account closures for non-residents. Some banks close accounts of customers who have moved abroad or ask for extra paperwork.
- Language and service issues, depending on the country.
- Less flexible apps than neobanks in some cases.
Use both
Many expats end up with a hybrid setup. There is nothing stopping you from keeping your existing traditional account while opening additional accounts abroad, online, in person or both. A sensible combination is:
- A local traditional bank account in the country where you live, for salary, rent, bills, savings and any loan or mortgage.
- A neobank or multi-currency account for international income, travel and currency exchange. See the best multi-currency accounts for freelancers and nomads.
- Your home country account, if you still need it for pensions, taxes or family.
- A backup account at a different provider.
Which is right for you?
| Your situation | Usually the best choice |
|---|---|
| You have just arrived and have no local address yet | A neobank first, then a local bank when you have documents |
| You live in one country long term | A local traditional bank as the main account |
| You are a digital nomad or move often | A neobank or multi-currency account, plus a home bank |
| You are paid by clients in several currencies | A multi-currency account |
| You plan to buy a home or need a loan | A traditional bank in that country |
| You need to receive a local salary | A traditional bank account, or check the employer accepts your neobank |
| You want in-person help and a long track record | A traditional bank |
A checklist for choosing
- Which country and which licence? Check whether the provider is a bank or an e-money institution, and which entity serves your country.
- What protection applies to your balance?
- What does it take to open the account and how long does it take?
- What are the total fees for the payments and cards you use?
- Which services do you need now and in the next two years (salary, loans, mortgage, savings)?
- How good is the support, and in which language?
- What are the limits on receiving, holding and withdrawing money?
- What is your backup plan?
Common mistakes to avoid
- Assuming a neobank is the same as a bank.
- Assuming a traditional bank is always safer than every digital option, or the reverse.
- Relying on a single account.
- Putting your whole emergency fund into a single app.
- Comparing headline fees instead of total costs.
- Opening a neobank account in the wrong country or entity.
- Forgetting that your employer needs to accept your account for salary.
- Ignoring local needs, such as loans or mortgages, until you need them.
- Closing your home account before you have a working local one.
Frequently asked questions
Is a neobank safe for expats?
It depends on the provider. A neobank with a banking licence usually offers deposit insurance on eligible deposits, while an e-money institution usually safeguards customer money. Check the licence and the entity that holds your money.
Can I open a traditional bank account as a new expat?
Often yes, but you usually need proof of address and other documents, and it can take longer. Neobanks can be a good first step while you settle in.
Can I receive my salary in a neobank account?
Often, but not always. Some employers or payroll systems do not accept it, so check before you give your details.
Which is cheaper for international payments?
Neobanks and multi-currency providers are often cheaper, because they use clearer pricing and lower margins, but compare the total cost for your own payments.
Do I need both a neobank and a traditional bank?
For many expats, yes. A traditional bank covers local essentials and borrowing, while a neobank covers international payments and travel.
Can a neobank close my account?
Yes, as can any bank. Reviews and closures can happen when verification is incomplete or activity looks unusual, so keep documents ready and have a backup.
Final thoughts
There is no single winner. Traditional banks give you stability, local services and in-person support, while neobanks give you speed, flexibility and cheaper international payments. For most expats, using both is the safest and most practical approach: a local bank for your everyday life and savings, a neobank or multi-currency account for your international income and travel, and a backup in case one of them has a problem. Whatever you choose, keep a cash reserve in a bank with deposit protection, and learn how to build an emergency fund designed for irregular income.
This article is general information, not financial advice. Products, rules and licences change and vary by country. Information reviewed October 6, 2026.
Sources and further reading
Official pages and primary sources where you can check the rules, fees and rates discussed in this guide. They are updated by their publishers, so check them for the current figures before you decide.
- Deposit guarantee schemes (European Commission)
- What FSCS covers (Financial Services Compensation Scheme (UK))
- Deposit insurance (FDIC (US))
- Bank accounts in the EU, including the right to a basic account (Your Europe (European Union))